
As of October 2026, choose a Dubai area by deciding first whether you will live in the home or rent it out: the two choices often lead to different districts. For a rental purchase, compare gross yield, tenant demand, the share of off-plan transactions and competing new supply; International City Phase 1 shows 8.21% gross yield, while Dubai Marina shows 5.66%. For living, test the actual commute, schools, transport, building age, density and service charges before paying for a recognised address. Market activity is lower than a year earlier: 181,510 transactions were registered in the previous 12 months, down 12.7% year on year, and the median transaction price was AED 1.443 million, down 7.1%.
Start with the purpose of the purchase
A buyer who needs a home and an investor buying for rent face different risks. A homebuyer may accept a lower gross yield for a daily routine that works: a manageable route to work, suitable schools, access to public transport, the distance to the coast if that matters, and a building whose maintenance standards can be assessed before signing. An investor has to ask a different question: who will rent this exact unit, at what level of rent, and how many similar units may compete with it?
Do not choose an area because it is described as “central”, “family-oriented” or “premium”. Those labels do not tell you whether the apartment is ready, whether the building has high annual service charges, or whether a large volume of off-plan stock is still being sold nearby. Use the Dubai area pages with transaction prices and deal activity to compare actual registered medians rather than asking prices.
The city median for a one-bedroom apartment over the 12 months through 23 October 2026 was AED 1.257 million. The median studio was AED 694,000 and the median two-bedroom apartment was AED 2.207 million. These are transaction medians, so they are reference points, not a promise that every listed apartment can be bought at that price.
A practical first split is simple:
- For your own use, shortlist areas only after testing the building, route and immediate surroundings at the times you would actually use them.
- For long-term rental, begin with a unit type and tenant profile, then compare rent, resale evidence, gross yield and new supply.
- For an off-plan purchase, separate the payment-plan price from ready-home resale prices. They are not interchangeable.
- If you may sell in a few years, avoid treating past price movement as a forecast.
PDF shortlist · updated 27 October 2026
New Dubai projects of October 2026
30 projects · prices from DLD and developers
-
 Rise By Athlon 1 Wadi Al Safa 5 · 1–3 BR
from AED 1,412,000
-
 Zuha Island Villas World Islands
from AED 68,000,000
-
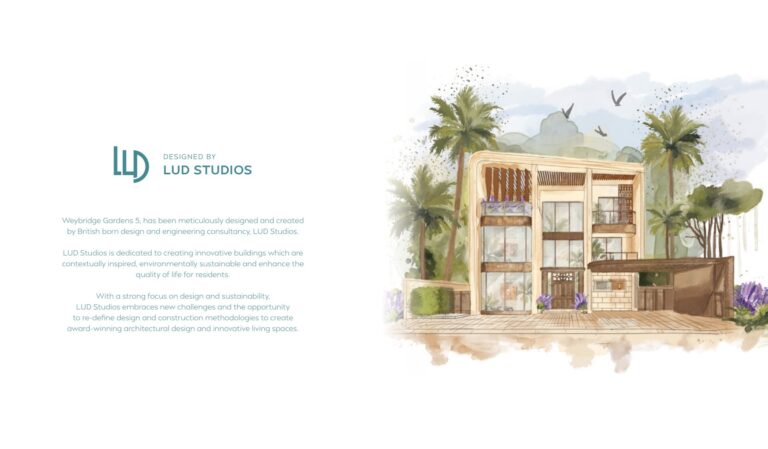 Weybridge Gardens Phase 5 by Leos Developments Dubailand Oasis
from AED 756,782
27 more in the PDF: prices, handover dates, payment plans
The PDF opens instantly. Refreshed monthly from DLD data.
Dubai transaction picture in October 2026
The figures below cover the 12 months from October 2025 to September 2026, with data through 23 October 2026. Dubai recorded 181,510 transactions worth AED 467.2 billion. Transaction count fell 12.7% year on year. In September 2026 alone, 11,479 transactions were registered, 43.5% fewer than a year earlier.
The median Dubai transaction price for the 12-month period was AED 1.443 million, compared with AED 1.550 million for 2025. The 2026 year-to-date median was AED 1.419 million. Median price per square foot was AED 1,722 over the 12-month period; that measure can rise while the median ticket price falls because the mix of units sold changes.
Off-plan represented 68.1% of transactions. That proportion matters because areas with a very high off-plan share can show many deals without offering much evidence of ready-unit resale pricing. Dubai Maritime City, for example, had 98.8% off-plan transactions; Palm Deira had 97.6%; JVT had 85.0%. A buyer considering rental income should not assume an off-plan-heavy area has a mature ready rental market.
Gross yield is published for specific area and unit segments, not for the city as a whole. It is calculated from rent and purchase price before service charges, maintenance, vacancy, furnishing, management, financing and transaction costs. It is not net income.
Comparison of 12 Dubai areas: prices, yield and supply
The table is a screening tool, not a ranking. A higher yield can reflect a lower entry price, a different tenant base, older housing stock, a more distant location, greater turnover, or a combination of these factors. A low off-plan share does not automatically make a district safer; it simply means more of the recorded activity was in ready or resale property.
| Area | Median 1BR, AED | AED/sq ft | Gross yield | Transactions | Off-plan |
| Dubai Marina | 1.620m | 1,980 | 5.66% | 2,398 | 8.3% |
| Downtown Dubai | 2.380m | 3,029 | 5.25% | 2,907 | 35.7% |
| Business Bay | 1.900m | 2,367 | 5.73% | 7,134 | 51.9% |
| JVC | 1.120m | 1,492 | 6.24% | 12,555 | 61.3% |
| JVT | 1.240m | 1,670 | 7.22% | 4,585 | 85.0% |
| Dubai Hills Estate | 1.740m | 2,400 | 6.02% | 2,411 | 59.4% |
| Dubai Creek Harbour | 1.950m | 2,564 | 5.65% | 4,005 | 67.3% |
| Palm Jumeirah | 3.450m | 2,597 | 5.24% | 1,323 | 31.4% |
| JLT | 1.550m | 1,707 | 6.69% | 849 | 23.0% |
| Arjan | 1.180m | 1,561 | 7.07% | 3,961 | 63.7% |
| Dubai Sports City | 1.010m | 1,309 | 7.71% | 3,394 | 62.3% |
| International City Phase 1 | 465,000 | 682 | 8.21% | 1,843 | 21.6% |
The apparent paradox is clear. Status-led districts such as Downtown Dubai, Palm Jumeirah and Dubai Marina produced gross yields of 5.25%, 5.24% and 5.66%. More budget-led areas recorded materially higher figures: Dubai Sports City 7.71%, Discovery Gardens 7.66%, International City Phase 1 8.21%, and Dubai Investment Park Second 8.60%. Al Barari reached 8.83%, although that figure relates to a villa segment with a median price of AED 5.07 million.
Higher gross yield should lead to more questions, not an automatic decision. Check the specific building, its service-charge history, lease demand for the unit size, the number of comparable listings and future construction near the property. The yield does not deduct any of those costs.
Areas for living: check the daily reality before the postcode
For a primary residence, the apartment has to work after the viewing ends. An address cannot substitute for a commute test, school availability, parking arrangements, lift waiting times, construction noise, traffic at peak hours or building management quality. View the unit in daytime and in the evening. If you have children, inspect the actual school route and confirm admissions directly with the school; availability depends on the individual school and year group.
Dubai Hills Estate, Dubai Creek Harbour, JVC, JVT, Business Bay, Dubai Marina, JLT, Sobha Hartland and the wider Jumeirah areas attract very different buyer profiles, but a name alone is not enough to establish suitability. For example, median one-bedroom prices were AED 1.740 million in Dubai Hills Estate, AED 1.950 million in Dubai Creek Harbour, AED 1.120 million in JVC and AED 1.240 million in JVT. That gap should be assessed alongside the actual apartment size, layout, building age and annual ownership costs.
Dubai Hills Estate recorded 2,411 transactions, with 59.4% off-plan. Dubai Creek Harbour recorded 4,005, with 67.3% off-plan. For a buyer deciding between the two for personal use, these figures describe market composition, not which area is “better”. Compare the exact buildings, handover status, access routes and the facilities you will use. Their one-bedroom gross yields were close: 5.88% for Dubai Hills Estate and 5.65% for Dubai Creek Harbour.
Older or mostly-ready districts can make physical inspection easier. Dubai Marina had only 8.3% off-plan transactions, JLT 23.0%, and JBR 0%. Newer supply-led areas require another layer of checking: identify nearby plots, active construction and planned phases, then decide whether you are comfortable living beside continued development. Do not rely on a brochure to answer that question.
Service charges can materially change the ownership budget, particularly where common facilities are extensive. Ask for the service-charge position for the exact unit and building, rather than applying an area average. Read how recurring charges affect a rental calculation in the guide to Dubai service charges and property returns.
Areas for rental income: demand matters more than a headline yield
A rental strategy begins with the property type. Dubai-wide, the median gross yield was 7.10% for studios and 5.55% for one-bedroom apartments. The difference does not mean studios are always preferable. A studio buyer must still check tenant demand in that building, the condition of the unit and competition from nearby stock.
JVC had the largest transaction count in the data, 12,555 deals, and a median one-bedroom price of AED 1.120 million. Its area gross yield was 6.24%, while the one-bedroom segment showed 7.00%. The off-plan share was 61.3%. This combination makes JVC a market where the buyer should compare the exact unit against both ready apartments and new launches, rather than assuming high transaction volume removes supply risk.
JVT showed a 7.22% gross yield, AED 1.240 million median one-bedroom price and 85.0% off-plan share. It had 4,585 transactions. For an investor, that high off-plan proportion is a reason to model future competing units rather than a reason to reject the district automatically.
Arjan and Dubai Sports City offer lower one-bedroom medians than many central districts: AED 1.180 million and AED 1.010 million. Their gross yields were 7.07% and 7.71%. Motor City recorded 7.83% gross yield, but its price per square foot fell 7.3% year on year and 78.9% of transactions were off-plan. The figures are a reminder that yield, resale price movement and supply mix can point in different directions.
International City Phase 1 is the clearest low-entry-price example in the comparison: median one-bedroom price AED 465,000, median rent AED 40,000 and one-bedroom gross yield 8.89%. The area-level yield was 8.21%. That does not make every apartment suitable for a first purchase. Building condition, leaseability, service costs and the legal status of the property still need individual review.
Price changes are evidence, not a forecast
Some buyers fear that they will buy immediately before a decline; others fear missing a rebound. Neither fear should be answered with a prediction. Use the year-on-year price-per-square-foot change to see what has already happened, then assess whether the exact property is comparable to the transactions behind the median.
Among the named areas, price per square foot rose 27.3% in DAMAC Hills, 20.5% in Dubai South Residential District, 18.9% in Palm Deira, 16.4% in Dubai Sports City, 14.0% in JVT, 13.9% in Arjan and 11.1% in Downtown Dubai. Dubai Creek Harbour rose 6.3%, Al Furjan 6.2% and JVC 4.4%.
Other areas declined: JLT fell 12.3%, Silicon Oasis 11.2%, Barsha Heights 10.1%, Dubai Marina 8.4%, Arabian Ranches-1 8.1%, Dubai Harbour 7.5%, Motor City 7.3% and DAMAC Hills 2 5.8%. Business Bay was close to flat at -0.8%, while Dubai Hills Estate was -0.2% and Palm Jumeirah was +0.1%.
Do not use an unusual movement as proof of future performance. A sharp change can reflect the mix of properties sold, particularly where few transactions or a large volume of off-plan deals affect the median. Areas where the annual movement is distorted by the mix of transactions are excluded from the comparison.
Rental data should also be read carefully. Median annual rent for a one-bedroom was AED 90,000 in Dubai Marina, AED 115,000 in Downtown Dubai, AED 85,000 in Business Bay, AED 70,000 in JVC and AED 53,000 in Dubai South Residential District. These are recorded medians, not assured rents for a future lease. This guide makes no claim that rents in a particular district will rise or fall.
Ready property, off-plan property and oqood
A ready apartment and an off-plan apartment require different checks. With ready property, inspect the condition, occupied or vacant status, current tenancy position, building records and the title documentation applicable to that unit. The practical purchase sequence is described in how to buy a ready property in Dubai. If you are ready to compare available homes after setting your criteria, use the catalogue of ready apartments rather than assuming a launch price is comparable to a completed unit.
For off-plan property, buyers often ask about oqood. Oqood is the Dubai registration system used for off-plan sales. The required registration, payment arrangements, project documentation and contractual terms depend on the transaction. The broker can explain the process and help prepare transaction documents, but a broker does not provide legal or tax advice. Ask a qualified lawyer or tax adviser for an opinion on your personal position.
Money should only move through the developer’s escrow arrangements or a trustee office as applicable to the transaction. A broker does not exchange or transfer client money, accept client funds, open bank accounts or issue loans. Financing terms and eligibility should be discussed directly with a bank.
Developer selection should also be evidence-based. Review the specific project, its registered transaction activity, delivery status and documentation. The developer pages with projects and transaction records can help narrow the list, but they do not replace legal review of a particular contract.
How to avoid buying in the wrong area
There is no single district that should be labelled the worst place to buy. The wrong area is one that conflicts with your purpose, budget or ability to hold the property through changing market conditions.
- Do not buy a high-yield unit before checking which costs are excluded from gross yield.
- Do not buy for family living without testing transport, school access and building conditions yourself.
- Do not treat a high off-plan share as proof of liquidity in the ready market.
- Do not use a district-wide median as a valuation for one tower, floor, view or layout.
- Do not buy a property whose payment obligations you do not understand; seek legal, tax or banking advice where required.
- Do not assume a recognised district will protect a buyer from a fall in price per square foot.
For a budget below about AED 500,000, the available median evidence is concentrated in International City Phase 1: AED 345,000 for a studio and AED 465,000 for a one-bedroom. At AED 800,000 to AED 1.2 million, the selection expands to studios and some one-bedroom apartments in JVC, Arjan, Dubai Sports City, Al Furjan, Motor City and Discovery Gardens. Two-bedroom medians in Dubai Marina, Business Bay, Dubai Hills Estate and Sobha Hartland were AED 2.600 million, AED 2.700 million, AED 2.690 million and AED 2.430 million respectively. A buyer should add the DLD fee, commission and other transaction or ownership costs to the property budget; these are not included in the medians.
See also: Dubai areas by DLD data: the 18 busiest districts in numbers · Dubai Marina in DLD numbers · Dubai Hills Estate in DLD numbers · Dubai Creek Harbour in DLD numbers · villas and townhouses by DLD data · studios by DLD data · Jumeirah in DLD numbers · Al Barsha in DLD numbers.
Frequently asked questions
Which Dubai area is best for buying an apartment to rent out?
There is no universal best area. International City Phase 1, Dubai Sports City, Motor City, Discovery Gardens, JVT and Arjan show gross yields from 7.07% to 8.21% at area level, but the decision must include the exact building, unit type, service charges, tenant demand and future supply.
Is JVC the best Dubai area for rental income?
JVC had the largest transaction count, 12,555, and a 6.24% area gross yield; its one-bedroom segment showed 7.00%. Its 61.3% off-plan share means investors should compare ready units with forthcoming competing stock.
Dubai Hills Estate or Dubai Creek Harbour: which is more profitable?
The data does not establish that either will be more profitable. Dubai Hills Estate showed 6.02% gross yield and AED 1.740 million median price for a one-bedroom; Dubai Creek Harbour showed 5.65% and AED 1.950 million. Both had off-plan shares above 59%.
Is Dubai South a good investment?
Dubai South Residential District recorded a AED 1.030 million median one-bedroom price, a 7.18% one-bedroom gross yield and 69.0% off-plan share. These figures warrant a unit-by-unit supply and rental-demand review; they do not guarantee income or price growth.
What is oqood?
Oqood is the Dubai registration system for off-plan property sales. The documents and registration requirements depend on the particular transaction. Ask a qualified lawyer for advice on contractual rights or legal consequences.
How do I decide which Dubai area to rule out?
Avoid any area or project where you cannot verify the unit’s status, ownership costs, supply context, payment obligations and fit with your purpose. A district with falling prices is not automatically unsuitable, and a district with a high yield is not automatically suitable.
Discuss a purchase in Dubai
If you are considering a purchase, arrange a free consultation to go through the property, the transaction steps and the documents.
PDF shortlist · updated 27 October 2026
New Dubai projects of October 2026
30 projects · prices from DLD and developers
30 more in the PDF: prices, handover dates, payment plans
The PDF opens instantly. Refreshed monthly from DLD data.