
As at October 2026, 74 Dubai off-plan projects first recorded in 2021–2024 showed a median increase of 10.6% in AED per sq ft from their first three months of registrations to the latest six-month period ending 27 October 2026. Twenty projects rose by 20% or more, while nine were below their launch-period median. In some projects the recorded price per sq ft is higher now than in the launch window, but the registry also shows flat and negative results, so buying at launch does not create a guaranteed gain. All prices below are in AED per sq ft; 2026 is incomplete because the registry extract ends on 27 October 2026.
What happened across the 74-project sample
The sample contains 74 projects with at least 30 recorded transactions in both comparison periods: the first three calendar months after the first off-plan registration, and the latest six months from 28 April to 27 October 2026. This threshold excludes smaller projects and projects with fewer than 30 recent transactions. It therefore reflects projects with a substantial recorded transaction history, rather than every launch in Dubai.
The median price change across these 74 projects was +10.6%. Twenty projects recorded an increase of at least 20%; nine showed a price per sq ft below the launch-period median. The median is not the return received by a particular buyer. It is the middle recorded price per sq ft after transactions are ranked, and it can move because buyers purchased different unit types, sizes and bedroom categories in each period.
For a person deciding whether to buy a launch today, this is the direct answer to the usual concern: yes, in some projects the later recorded price per sq ft was higher. No, that pattern did not apply to every project in the sample, including projects with dozens or hundreds of transactions. A launch price should be treated as the price of a specific unit under a specific payment schedule, not as proof of future appreciation.
The figures compare AED per sq ft. They do not include instalments already paid, financing costs, registration-related costs, brokerage costs, service charges after handover, rental vacancy, furnishing, taxes in the buyer’s country of residence, or the time needed to find a purchaser. For any buyer with cross-border tax obligations, a tax adviser should assess the personal position.
PDF shortlist · updated 27 October 2026
New Dubai projects of October 2026
30 projects · prices from DLD and developers
-
 Rise By Athlon 1 Wadi Al Safa 5 · 1–3 BR
from AED 1,412,000
-
 Zuha Island Villas World Islands
from AED 68,000,000
-
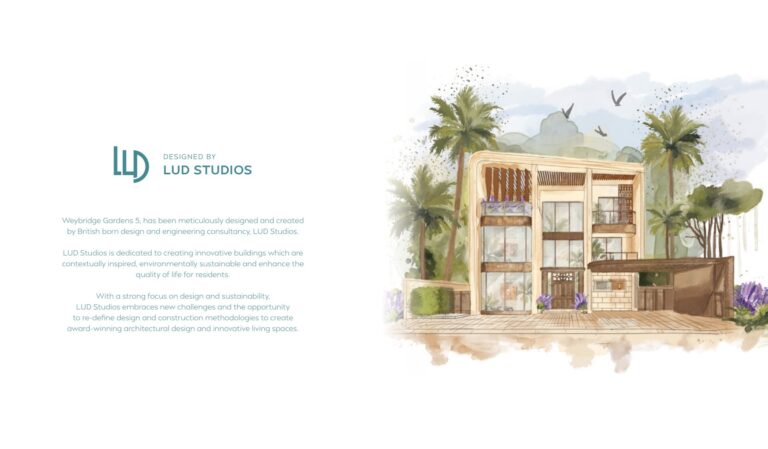 Weybridge Gardens Phase 5 by Leos Developments Dubailand Oasis
from AED 756,782
27 more in the PDF: prices, handover dates, payment plans
The PDF opens instantly. Refreshed monthly from DLD data.
How the comparison was calculated
“Launch” in this page does not mean an official marketing launch date. It means the date of the first off-plan transaction recorded for a project number. The first recorded transaction may follow closed sales or an EOI stage, or it may be an isolated early registration before broader sales began. Projects with an earlier off-plan record were not included, even if they had active sales in 2021–2024.
The launch window is the first three calendar months from that first registry record and includes off-plan transactions. The current window is the six months from 28 April 2026 to 27 October 2026 and includes both off-plan and existing-property transactions. In the tables, “existing share” means the share of latest-window transactions registered as Existing Properties; the remainder is off-plan, including new sales and contract assignments.
The registry does not separate a developer’s first sale from an assignment of an off-plan contract. Both can appear as Sell – Pre registration, commonly described by buyers as Oqood. In the first three months, transactions are mostly initial sales, but the registry field alone does not prove that every entry was a primary sale.
For this reason, a resale comparison is not an investor return calculation. In several projects, the latest transactions are entirely in completed homes and are therefore secondary-market deals. In others, the latest period remains entirely off-plan. A buyer considering a particular developer can review recorded projects and transactions through the developer pages with projects and transaction data, while area-level price and deal comparisons are available through the Dubai area pages with DLD prices and transactions.
Comparing a studio with a three-bedroom home solely because they share a project name can produce a misleading result, so compare like with like by unit type and size.
The highest values in the sample, not a typical outcome
The following table shows the 20 highest price-per-sq-ft increases among the 74 qualifying projects. It is not a list of “best” projects and is not a typical result. The table is sorted by price change only; sorting is a reading order, not an assessment of a project, developer or area.
| Project | DLD area | Launch median | Latest median | Change | Deals: launch / latest | Existing share latest | Largest bedroom type change |
|---|---|---|---|---|---|---|---|
| Rukan 3 | Wadi Al Safa 7 | 605 | 1,581 | +161.5% | 113 / 41 | 100% | 1 B/R: +139% (60 / 24) |
| Aura | Al Hebiah Fourth | 1,082 | 2,535 | +134.3% | 286 / 35 | 100% | 4 B/R: +127% (197 / 16) |
| The Valley – Orania | Al Yufrah 1 | 830 | 1,363 | +64.2% | 288 / 36 | 100% | 3 B/R: +68% (219 / 24) |
| Mudon Al Ranim 4 | Al Hebiah Sixth | 1,131 | 1,749 | +54.6% | 106 / 32 | 100% | 3 B/R: +56% (60 / 18) |
| Bianca | Wadi Al Safa 2 | 836 | 1,281 | +53.2% | 96 / 33 | 0% | 2 B/R: +53% (73 / 27) |
| The Valley – Elora | Al Yufrah 1 | 1,109 | 1,672 | +50.8% | 328 / 56 | 100% | 3 B/R: +54% (208 / 34) |
| SERENIA LIVING | Palm Jumeirah | 3,028 | 4,513 | +49.0% | 216 / 35 | 100% | 2 B/R: +52% (97 / 21) |
| TORINO BY ORO24 | Al Barshaa South Third | 1,135 | 1,660 | +46.2% | 331 / 44 | 100% | Studio: +44% (147 / 14) |
| Mudon Al Ranim 6 | Al Hebiah Sixth | 1,230 | 1,770 | +43.9% | 240 / 49 | 84% | 3 B/R: +39% (140 / 37) |
| Peninsula Two | Business Bay | 1,798 | 2,562 | +42.5% | 284 / 39 | 100% | Studio: +54% (132 / 15) |
| Mudon Al Ranim 5 | Al Hebiah Sixth | 1,298 | 1,804 | +39.0% | 170 / 42 | 88% | 3 B/R: +39% (98 / 26) |
| The Hamilton | Al Yelayiss 2 | 1,065 | 1,358 | +27.5% | 213 / 41 | 100% | 2 B/R: +33% (96 / 25) |
| SKYZ By Danube | Al Barshaa South Third | 1,193 | 1,502 | +25.9% | 286 / 50 | 100% | Studio: +24% (129 / 28) |
| Regalia | Business Bay | 1,399 | 1,751 | +25.1% | 719 / 78 | 56% | 1 B/R: +26% (448 / 54) |
| TRIA BY DEYAAR | Nadd Hessa | 1,069 | 1,323 | +23.8% | 169 / 31 | 0% | Studio: +18% (64 / 10) |
| THE MAYFAIR | Al Yelayiss 2 | 1,077 | 1,333 | +23.8% | 211 / 43 | 77% | 1 B/R: +16% (95 / 15) |
| Arabian Ranches lll – Raya | Wadi Al Safa 5 | 1,265 | 1,563 | +23.5% | 206 / 40 | 100% | 3 B/R: +50% (147 / 19) |
| Palace Residences – North | Al Khairan First | 2,108 | 2,595 | +23.1% | 296 / 36 | 100% | 2 B/R: +25% (117 / 17) |
| Peninsula Three | Business Bay | 2,118 | 2,607 | +23.1% | 519 / 76 | 100% | 1 B/R: +22% (299 / 46) |
| Hills Park | Hadaeq Sheikh Mohammed Bin Rashid | 1,799 | 2,206 | +22.7% | 395 / 38 | 100% | 1 B/R: +22% (204 / 24) |
The bedroom-type column is included because it tests whether the project-level result is broadly visible in the most frequently traded bedroom category. It can differ materially from the project median. For example, Peninsula Two rose 42.5% across all recorded types, while its most frequent studio category rose 54%.
Five large projects with moderate recorded increases
High-ranking cases can distort expectations. The next five projects were selected outside the top 20 because they had price changes from +3% to +15% and the largest combined number of transactions in the two periods. They show a different part of the same 74-project sample.
| Project | DLD area | Launch median | Latest median | Change | Deals: launch / latest | Existing share latest | Largest bedroom type change |
|---|---|---|---|---|---|---|---|
| AZIZI VENICE 14 | Madinat Al Mataar | 1,585 | 1,652 | +4.3% | 162 / 1,888 | 0% | Studio: +5% (99 / 1,411) |
| SOBHA ONE | Ras Al Khor Industrial First | 2,150 | 2,285 | +6.3% | 1,849 / 94 | 0% | 1 B/R: +4% (963 / 50) |
| Sobha Creek Vistas Heights | Al Merkadh | 2,003 | 2,076 | +3.6% | 1,075 / 59 | 0% | 1 B/R: +1% (627 / 39) |
| Sobha Hartland – The Crest | Al Merkadh | 1,925 | 2,130 | +10.7% | 879 / 65 | 100% | 1 B/R: +11% (516 / 38) |
| Binghatti Skyrise | Business Bay | 2,293 | 2,403 | +4.8% | 734 / 35 | 0% | Studio: +2% (499 / 19) |
These figures are useful for a buyer who is uncomfortable with a sales presentation based only on exceptional past cases. A +4.3%, +4.8% or +6.3% median movement is still a positive change in recorded price per sq ft, but it is very different from the values at the top of the sample. It also remains before the buyer’s own costs.
Projects where the latest median was lower
Nine qualifying projects had a latest median below their launch-period median. This does not identify why each movement occurred, nor does it determine the price of any individual unit. It does answer the concern that a buyer may be unable to resell above the launch price: that outcome appears in the recorded data.
| DLD area | Launch median → latest median | Change | Deals: launch / latest |
|---|---|---|---|
| Wadi Al Safa 5 | 1,502 → 1,343 | -10.6% | 200 / 54 |
| Wadi Al Safa 5 | 1,580 → 1,447 | -8.5% | 43 / 41 |
| Madinat Al Mataar | 1,834 → 1,709 | -6.8% | 61 / 233 |
| Business Bay | 2,348 → 2,229 | -5.0% | 247 / 69 |
| Business Bay | 2,744 → 2,625 | -4.3% | 138 / 46 |
| Madinat Dubai Almelaheyah | 2,748 → 2,656 | -3.4% | 493 / 37 |
| Al Barsha South Fourth | 1,462 → 1,425 | -2.5% | 173 / 31 |
| Al Khairan First | 2,304 → 2,281 | -1.0% | 82 / 61 |
| Zaabeel First | 2,660 → 2,653 | -0.3% | 1,636 / 47 |
No project with fewer than 30 transactions in either window is included in these comparisons. Such observations should be treated as individual transactions rather than as a project-level median trend.
Why the unit type matters more than a headline project median
The registry does not contain a transaction-level link to floor and view. It records the area, master project, project, building, subtype, bedroom count, area and price, but not a usable floor-and-view comparison for these transactions. A difference between two units may therefore reflect characteristics that cannot be measured here.
Bedroom categories nevertheless show a visible spread at launch. In Regalia, the project-wide launch median was 1,399 AED per sq ft. The median for 1 B/R units was 1,386 across 448 sales; Studio units were 1,525 across 146 sales; 2 B/R units were 1,408 across 95 sales; and 3 B/R units were 1,359 across 29 sales. The overall project figure is not the launch price of every apartment.
In The Valley – Elora, the launch median was 1,109 AED per sq ft. The recorded 3 B/R median was 1,123 across 208 sales, while 4 B/R was 810 across 120 sales. The registry data does not establish the reason for this gap; it may be affected by how the registered area is recorded for villas or townhouses.
Before reserving, compare the intended unit against units with the same bedroom count and a similar recorded size. Ask for the payment schedule, completion date stated in the contract documents, treatment of assignment, and all charges payable by the buyer.
What a launch buyer should check before paying an EOI
An EOI is an expression of interest used before or during allocation. Its refund conditions depend on the signed form, the developer’s process and the reason for cancellation. Read the refund wording before payment and retain the signed copy; the practical questions are covered in the guide to EOI and deposit refunds in Dubai.
For an off-plan purchase, ask which project account receives each payment, what documentation will be issued, and how the registration process will be handled. A broker can explain the sequence, compare recorded transactions, help prepare documents and accompany the transaction. The broker does not accept or transfer client money: off-plan payments should go only to the project escrow account.
Construction timing and handover remain separate risks from price movement. Read the explanation of off-plan risks, escrow and delays before treating a completion date as certain. If a plan includes instalments after handover, compare the actual dates and amounts rather than relying on a headline percentage; current formats are collected on the Dubai developer payment plans page.
Gross rental yield is also not the same as net income. A gross yield compares rent and property price before ownership costs, while a personal calculation must account for costs and the actual rental period. For that distinction, use the guide to calculating net rental yield. It is not possible to infer a buyer’s rental result from these launch-versus-current price comparisons.
See also: EOI and pre-launch booking: how the best units are allocated.
Frequently asked questions
Did people really buy at launch and later sell for more?
In some projects, yes: the recorded price per sq ft was higher later. In this 74-project sample, the median project change was +10.6%, and 20 projects recorded increases of 20% or more in AED per sq ft, while nine were below zero. Rukan 3 moved from 605 to 1,581 AED per sq ft, but that is one high-value case rather than a typical result. The registry does not show who sold or at what profit.
Which launches rose the most in the recorded data?
Rukan 3 showed +161.5%, Aura +134.3%, and The Valley – Orania +64.2%. Their latest periods contained 41, 35 and 36 transactions respectively, and all of those latest transactions were recorded as existing-property sales.
Were any launches cheaper later than at the start?
Yes. Nine of the 74 projects had a lower latest median than at launch, with changes between -0.3% and -10.6%.
Is the 10.6% figure a guaranteed return for an investor?
No. It is the median change in recorded AED per sq ft across 74 projects, not a return after instalments, fees, service charges, financing, holding period or taxes. It also mixes different unit types unless the bedroom-specific figure is used.
Does “launch” mean the official day sales opened?
No. It means the month of the first off-plan transaction recorded for that project number. The official sales launch may have been earlier or later than that first registry entry.
Can I treat Oqood resale prices as primary developer prices?
No. The registry does not distinguish a primary developer sale from an assignment of an off-plan contract where both are recorded as Sell – Pre registration. Oqood should be checked against the particular contract, payment history and assignment conditions.
Discuss a purchase in Dubai
If you are considering a purchase, arrange a free consultation to go through the property, the transaction steps and the documents.
PDF shortlist · updated 27 October 2026
New Dubai projects of October 2026
30 projects · prices from DLD and developers
30 more in the PDF: prices, handover dates, payment plans
The PDF opens instantly. Refreshed monthly from DLD data.